VAT Invoice Requirements UK: Full, Simplified and Modified Invoices
If you are VAT registered, your invoices must show specific details for your customer to reclaim VAT. Here is the full HMRC checklist, plus when simplified and modified invoices are allowed.
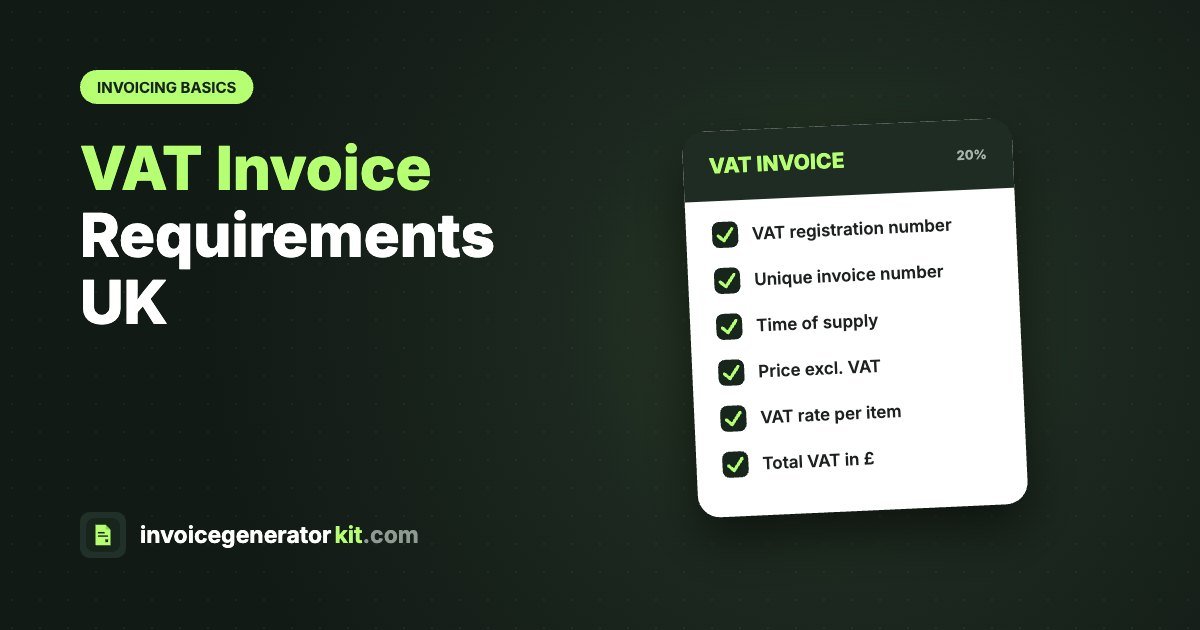
A UK VAT invoice must show a unique invoice number, your business name and address, your VAT registration number, the invoice date, the time of supply if it is different, your customer's name and address, a description of each item, the quantity and price excluding VAT, the VAT rate for each item, the total excluding VAT, any discount and the total VAT charged in pounds sterling. You normally have to issue it within 30 days of the supply.
Without these details your customer cannot reclaim the VAT, so getting them right protects your client relationships as well as your own records.
Who needs to issue VAT invoices?
Only VAT-registered businesses. You must register when your VAT-taxable turnover goes over £90,000 in any rolling 12-month period, and you can register voluntarily below that. If you are not registered, you must not charge VAT or show a VAT number. Once registered, you must give a VAT invoice to any VAT-registered customer you sell to.
The full VAT invoice checklist
| Detail | Notes |
|---|---|
| Unique invoice number | Must follow on from the last one. See how to number invoices |
| Your business name and address | Trading name and address |
| Your VAT registration number | 9 digits, usually shown as GB123456789 |
| Invoice date | The date you issue it |
| Time of supply (tax point) | Only if different from the invoice date |
| Customer name and address | Or trading name |
| Description of goods or services | Clear enough to identify what was supplied |
| Quantity and unit price excluding VAT | For each line |
| VAT rate for each item | 20%, 5% or 0% |
| Total excluding VAT | Plus any discount offered |
| Total VAT | Always in pounds sterling |
If you trade as a limited company you also need your registered name, company number, place of registration and registered office. Our invoice checklist covers those general rules.
Full vs simplified vs modified VAT invoices
| Type | When you can use it | What changes |
|---|---|---|
| Full VAT invoice | Any supply | Shows everything in the checklist above |
| Simplified VAT invoice | Retail supplies of £250 or less including VAT | Can show the VAT-inclusive total and the VAT rate per item, without a separate VAT figure; customer details not needed |
| Modified VAT invoice | Retail supplies over £250, if the customer agrees | Shows VAT-inclusive prices per line, plus the totals excluding VAT, the VAT and the total including VAT |
VAT invoice example
| Description | Qty | Unit price | VAT rate | Net |
|---|---|---|---|---|
| Bookkeeping, October | 1 | £300.00 | 20% | £300.00 |
| Printed tax guide | 2 | £15.00 | 0% | £30.00 |
| Total excluding VAT | £330.00 | |||
| VAT at 20% | £60.00 | |||
| Total due | £390.00 | |||
Our free invoice generator lets you add your VAT number, set a tax rate and shows the VAT breakdown automatically, so the totals always add up.
Special cases
Domestic reverse charge (construction)
For building and construction services covered by the domestic reverse charge, you do not charge VAT to the customer. The invoice must still show the VAT rate and amount, and clearly state that the reverse charge applies and the customer must account for the VAT to HMRC.
Foreign currency
You can invoice in euros or dollars, but the total VAT must also be shown in sterling.
Correcting a VAT invoice
Never edit or delete an invoice once it is sent. Issue a credit note and, if needed, a new invoice. See credit note vs invoice.
Common VAT invoice mistakes
- Missing or wrong VAT number, the most common reason customers reject invoices.
- Showing only a VAT-inclusive total on a sale over £250.
- Charging VAT before your registration date.
- Reusing or skipping invoice numbers.
- Issuing the invoice more than 30 days after the supply without agreement from HMRC.
How long to keep VAT invoices
Keep VAT records, including copies of every invoice you issue and receive, for at least 6 years. VAT-registered businesses must also keep digital records and file returns using Making Tax Digital compatible software. The official rules are in HMRC's VAT guide (Notice 700).
Frequently asked questions
What makes an invoice a valid VAT invoice?
It must be issued by a VAT-registered business and show a unique number, your name, address and VAT number, the invoice date, the time of supply if different, the customer’s name and address, a description of each item, the price excluding VAT, the VAT rate, the totals excluding VAT and the total VAT in sterling.
How long do I have to issue a VAT invoice?
Normally within 30 days of the date of supply, or of the date you received payment if the customer paid in advance.
Can I use a simplified VAT invoice?
Yes, if you are a retailer and the supply is £250 or less including VAT. A simplified invoice can show the VAT-inclusive total rather than a full VAT breakdown.
Do I need to issue a VAT invoice for zero-rated sales?
You do not have to issue a VAT invoice if the invoice is only for exempt or zero-rated sales within the UK, although a normal invoice is still good practice.
Can a VAT invoice be in a foreign currency?
Yes, but the total VAT must also be shown in pounds sterling, using an acceptable exchange rate.
Create your invoice now
Add your logo, line items and tax, see it on a real A4 page, then download a clean PDF. Free, with no sign up.